What The Hell Happened This Week?
Loading…
Oil above $100 was the headline. The bigger story was the convergence: renewed energy pressure, a jump in Fed-hike odds and the 10-year Treasury pushing toward 5%.
The week
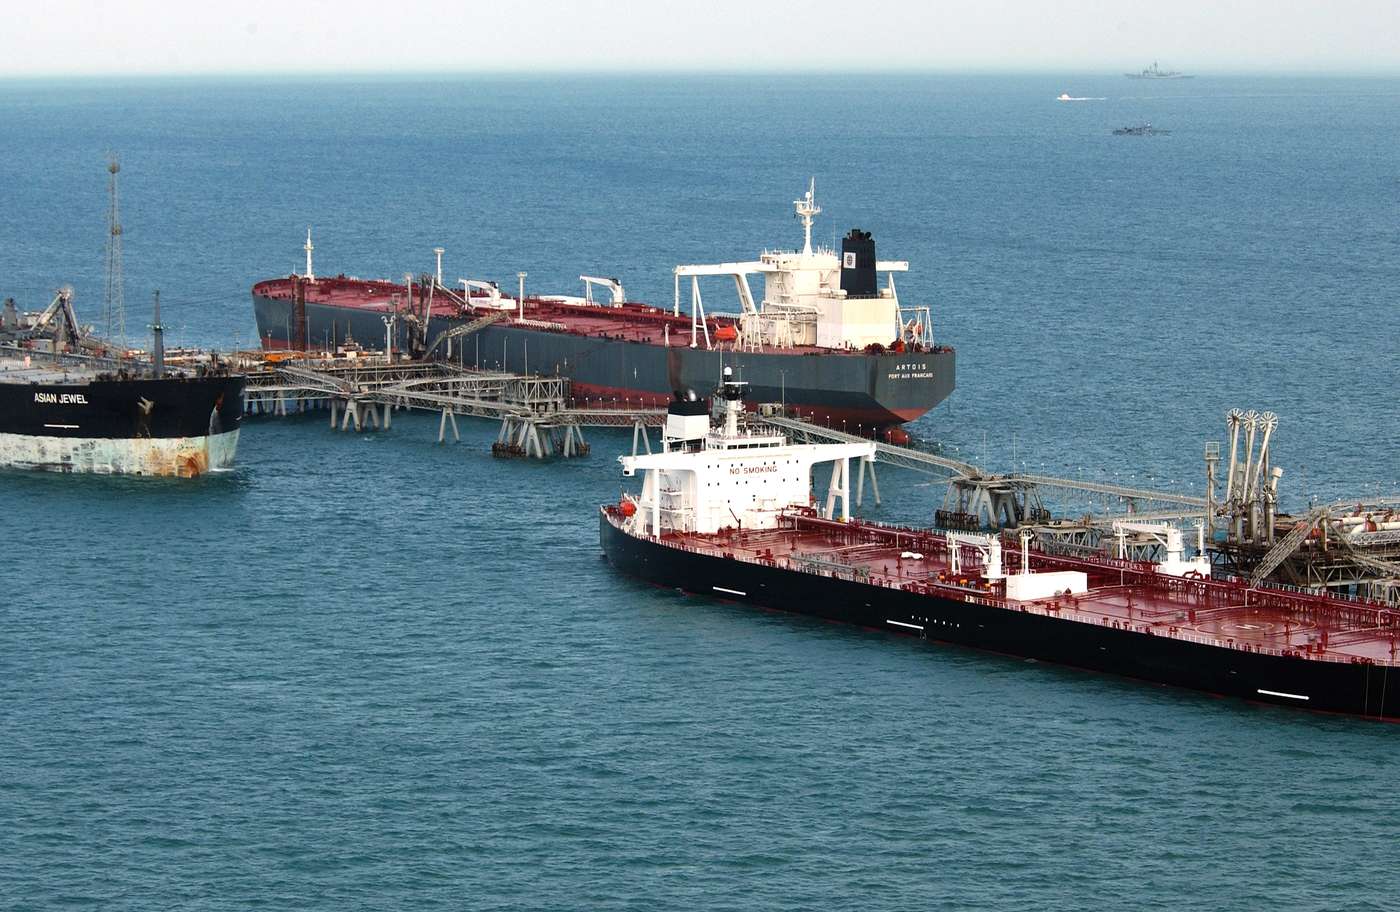
Brent crude futures broke through $100 a barrel during the week and traded as high as $109.97 on Friday as Gulf supply risk intensified.
That was the headline.
The number that showed why the week mattered beyond oil was 4.99% — roughly where the 10-year U.S. Treasury yield traded intraday on Friday.
By this point, energy had already been a major force in headline inflation. The new question was whether a renewed leg of the oil shock would deepen the policy and bond-market problem.
By Friday, several things had converged: higher crude, still-elevated headline inflation, firmer core inflation, a sharp move in market-implied Fed-hike odds, an ECB rate increase and a 10-year Treasury yield pressing against 5%.
The shortcut is:
oil goes up → inflation gets worse → central banks tighten → bond yields rise
It is not wrong. It skips the machinery that matters.
In lay terms: oil was the shock. The bond market was the transmission line.
If higher energy costs make inflation harder to extinguish, central banks may need to keep money tighter. And if investors demand a higher return to lend for years, that Treasury yield becomes an input into the price of borrowing across much of the economy.
Two guardrails matter from the start.
September’s oil surge did not cause August’s CPI report.
And oil did not cause every basis point of the Treasury move. In fact, the biggest jump in market-implied Fed-hike odds on Friday came after the CPI release. Oil mattered because it raised the forward inflation risk policymakers and bond investors had to weigh — not because we can assign it a precise share of the week’s repricing.
The important part
An energy shock becomes system-wide when it changes the benchmark price of long-term money.
Three things looked different by Friday.
First, the renewed oil shock became more consequential.
Brent futures began the week around $97.50, crossed $100 and touched nearly $110.
Energy was already doing a lot of work inside headline inflation. August CPI rose 0.4% for the month and 3.4% from a year earlier. Gasoline rose 3.9% in August and accounted for more than one-third of the monthly increase.
Core prices also rose 0.3% for the month.
So the September move was not creating an inflation problem from scratch. It was adding a fresh supply risk to an inflation picture that was already uncomfortable.
Second, the expected policy path moved.
Immediately before Friday’s CPI release, market pricing put the probability of a quarter-point Fed rate increase at roughly 67%.
After the data, that moved to about 85%.
That does not prove oil caused the repricing. The largest step followed the inflation data itself.
What oil changed was the forward-looking question: if energy costs remained high or rose again, would the inflation problem become harder to contain?
Third, the benchmark price of long-term money rose.
The 10-year Treasury traded around 4.99% intraday on Friday. Treasury’s official September 11 par-yield reading was 4.96%.
That matters because Treasuries are not just another asset class. They are part of the pricing infrastructure underneath mortgages, corporate bonds, asset valuations and other long-term financing decisions.

There were really two lanes feeding the same financial result.
The point is not that oil caused everything.
The point is that a renewed oil shock can add pressure to a financial system that is already repricing.
The financing chain underneath the story is simple:
Bond investors → cash → U.S. government
U.S. government → fixed future payments → bond investors
If investors require a higher return for that claim, the bond’s price has to fall until the yield becomes attractive enough.
Then the benchmark travels outward:
Treasury yield + borrower-specific spread → private borrowing cost
The oil shock does not send cash directly into a mortgage or corporate bond.
It changes the inflation and policy risks that help determine the benchmark against which many of those loans and securities are priced.
A central bank cannot produce a barrel of oil.
If a supply disruption makes energy more expensive, raising interest rates does not repair the shipping route, create more crude or reverse the original physical shortage.
What a central bank can do is try to stop the first price increase from spreading.
Higher fuel costs can reach the economy through several doors.
Consumers have less money left after filling the tank. Airlines, manufacturers, logistics companies and chemical producers face higher input costs. Businesses then decide how much of that cost to absorb and how much to pass on.
The deeper risk is persistence: a temporary supply shock could begin affecting broader prices, wage demands and inflation expectations.
That is the central-bank dilemma.
Rates can cool demand elsewhere in the economy, but the cure can weaken growth without fixing the original energy problem.
This week, that trade-off became more uncomfortable because headline inflation was still elevated and core prices firmed in August.
Europe reinforced the point.
On September 10, the European Central Bank announced a 25-basis-point increase in all three key policy rates, taking the deposit facility rate to 2.50% effective September 16.
The tightening pressure was not confined to the United States.
Now move from the central bank to the bond buyer.
Imagine a 10-year Treasury that promises a fixed stream of future payments.
If investors require a higher return to own those payments, the bond’s price has to fall until the return becomes attractive enough.
Same promised cash flows.
Lower price.
Higher return.
That return is the bond’s yield.
No committee simply declares that the 10-year Treasury should yield 5%. No single investor sets it either.
The price emerges through trading as buyers and sellers meet at a return high enough for the market to clear.
At the margin, the next buyer matters because somebody has to be willing to take the next unit of risk at the offered price.
What goes into that required return?
One part is the path investors expect short-term interest rates to take over the coming years. If the Fed is expected to keep rates higher, that can pull long yields upward.
But a 10-year investor is also locking money up while inflation, fiscal policy, bond supply, growth and other conditions can change.
Investors may demand extra compensation for carrying that long-horizon uncertainty.
Finance calls that extra compensation the term premium.
The term premium is not a separate number printed next to the Treasury yield. It is estimated, and different models can produce different estimates.
So the useful point is not that “the term premium rose by X this week.”
It is that the 10-year yield contains more than the next Fed decision.
For the renewed oil shock to matter, it did not have to explain the entire Treasury selloff. It only had to add to the inflation and policy risks facing investors while other forces were already pushing on long-term yields.
One of the week’s less glamorous events makes the distinction clearer.
On September 10, Treasury offered to buy back as much as $6 billion of face value in bonds maturing in roughly 10 to 20 years.
Eligible counterparties submitted $10.489 billion of face value.
Treasury accepted $5.187 billion of face value.
Those are face-value numbers, not the amount of cash Treasury paid.
Many of the accepted bonds were older, low-coupon securities trading below par. Based on the accepted prices, the clean purchase cost was roughly $3.66 billion before accrued interest.
At first glance, a large government buyer entering the long-bond market sounds like something that should push yields down.
And buybacks can support long-end prices at the margin.
But Treasury’s own program documents describe the primary purpose of these liquidity-support buybacks differently: give the market a regular, predictable outlet for older Treasury securities that trade less actively.
When a newer benchmark bond is issued, older versions can become harder to trade without giving up price.
The market calls those older securities off the run.
Buying some of them back can make that corner of the market work better.
What the operation cannot do is dictate the return investors must accept to own long-term U.S. debt.
That is the distinction:
Treasury can make some bonds easier to trade. It cannot make investors stop demanding more to own them.
The same market can become more liquid and still clear at a higher yield.
And we cannot observe the counterfactual. Yields might have been even higher without the buyback.
So the useful conclusion is not that the operation had no effect.
It is that a liquidity-support operation does not mechanically set the market-wide yield.
Why should anyone outside a Treasury trading desk care whether the 10-year yield is 4.5%, 4.8% or 4.96%?
Because that yield becomes a starting point for other prices.
Take a simplified 10-year corporate bond.
Suppose a new issue or refinancing has to pay 2 percentage points more than a comparable 10-year Treasury to compensate investors for the company’s credit risk.
If the Treasury benchmark is 4.96% and the spread is unchanged at 2 percentage points, the required yield is roughly 6.96%.
Nothing had to happen to the company’s credit spread.
Its borrowing cost still rose because the benchmark underneath it moved.
Actual corporate pricing also depends on credit quality, liquidity, maturity, covenants and issue structure. But the mechanism is the same.
That logic travels through the financial system.
Mortgages: mortgage rates are not mechanically equal to the 10-year Treasury. They are also shaped by mortgage-backed securities pricing and other factors. But higher long-term government yields usually increase the pressure on mortgage financing costs.
Corporate bonds: fixed-rate companies borrow at a spread over a government benchmark. If the Treasury benchmark rises, a new issue or refinancing can become more expensive even if the credit spread does not change.
Leveraged loans: these often float over short-term benchmarks such as SOFR rather than the 10-year Treasury. That means the expected Fed path and short rates matter more directly for them.
Equities: when safer long-term yields rise, future corporate cash flows are discounted at a higher rate. All else equal, cash flows far in the future become worth less today.
The government itself: as Treasury debt matures and is refinanced, higher rates across the curve tend to raise federal interest expense over time. The relevant rate depends on the maturity being rolled over.
This is the financial transmission the headline misses if oil, central-bank expectations and bond yields are treated as unrelated numbers.
The mechanism is real, but it is not automatic.
If oil falls back quickly, part of the forward inflation concern can fade.
If higher energy costs squeeze spending enough, weaker demand elsewhere can offset some of the inflation pressure.
If longer-term inflation expectations remain anchored, central banks may decide the shock does not require as much additional restraint.
And if bond investors become willing to accept lower required returns, Treasury yields can fall even while energy remains expensive.
Friday itself was a reminder that the market was not moving in one clean direction.
Oil eased from its intraday high and stocks rallied.
That does not erase the week’s state change.
It tells us not to confuse a transmission mechanism with a one-way forecast.
The useful lesson is not:
oil makes interest rates go up.
That is too simple.
The lesson is that an energy shock becomes system-wide when it changes the benchmark price of long-term money.
It begins with something physical: energy costs more.
Then comes the economic question: will that make inflation more persistent?
That can change the expected policy path.
Bond investors then decide what return is sufficient to lend for years under the new mix of risks.
And once the Treasury benchmark changes, borrowers and investors throughout the economy have to redo their math.
Oil was the shock. The bond market was the transmission line.
The next time oil spikes and interest rates start moving, ask:
Those questions separate the initiating headline from the financial machinery underneath it.
The week ended with oil above $100.
The more important change was that the shock had reached the cost of money.
Every figure in this issue is sourced either to a primary release or to contemporaneous reporting from the week it describes. The editorial information set is frozen at the close of Friday, 11 September 2026: later developments were used only to check the sources, never to improve the issue with hindsight. Market-implied probabilities and intraday prices are observations at a moment rather than settled facts, and are labelled that way. Where a relationship is genuinely multi-causal — most importantly the move in long-term Treasury yields — the issue says so instead of assigning a single cause. Treasury buyback amounts are face (par) values; the roughly $3.66 billion clean purchase cost is an In Lay Terms calculation from Treasury's security-level results, before accrued interest.
Your turn
Was something unclear? Did we miss an important angle? Is there a question you’d like us to answer next?
We’d love to hear from you.
Share your thoughtsor write to hello@inlayterms.com
Spotted a factual error? Write to corrections@inlayterms.com.